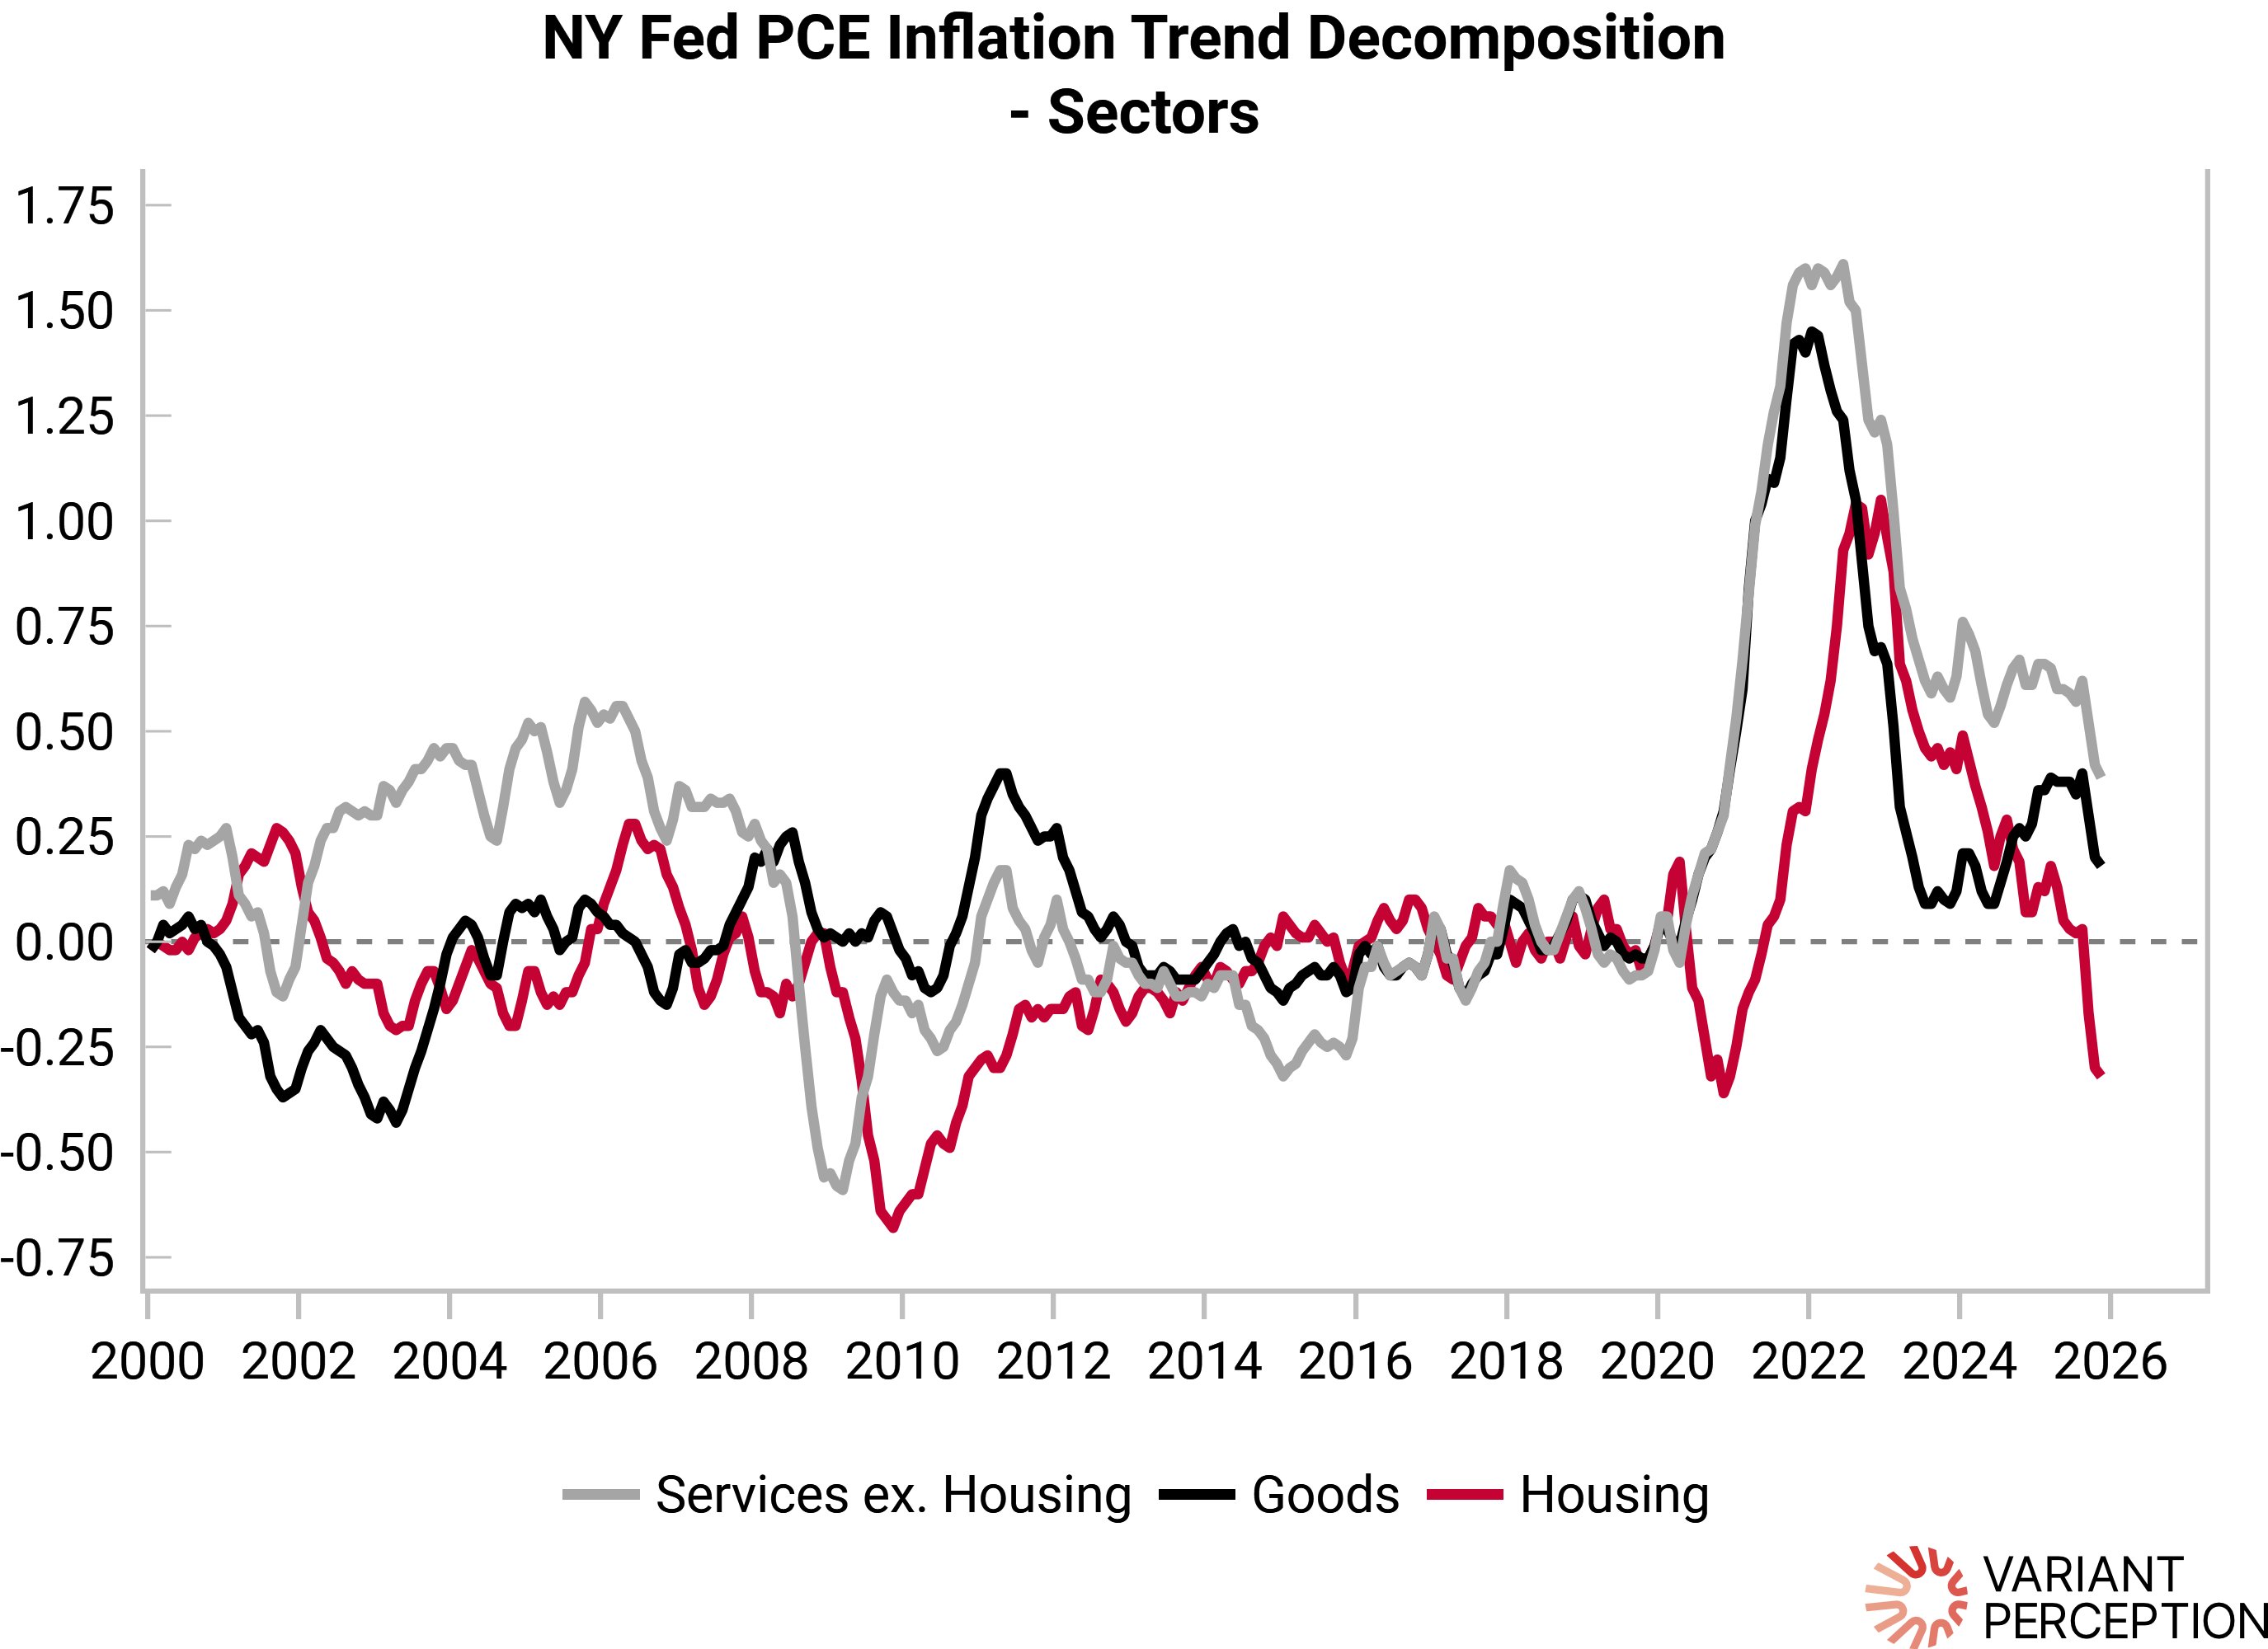
Chart of the Week
***
Research This Week
LEIs steady, incoming data marginally worse - Feb. G3 LIW | [Watch Discussion]
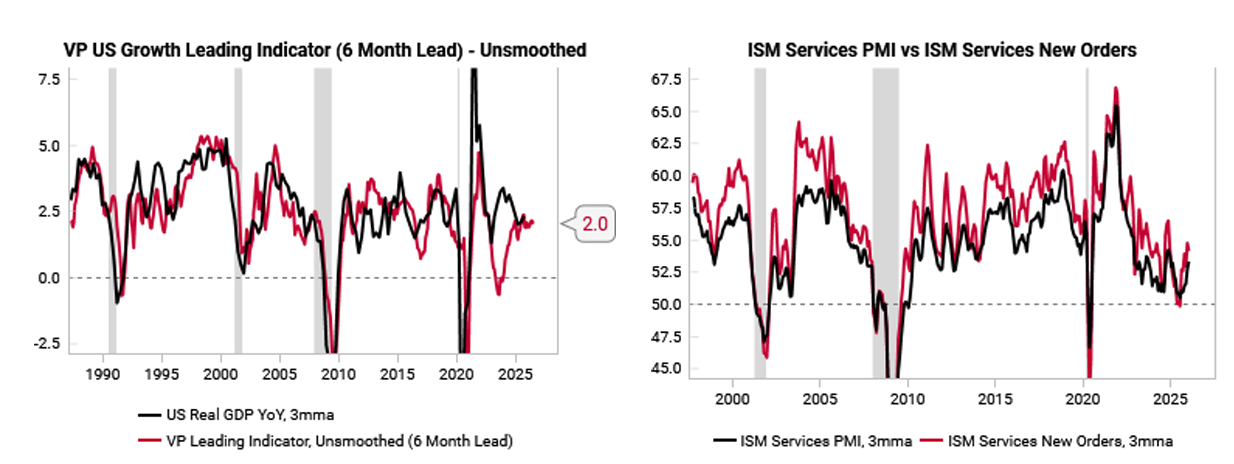
- US: Leading indicators are steady overall, but incoming data have worsened relative to a month ago. On balance, dissaving from the government and household sectors, along with a pick up in AI-driven capex, are supportive of growth.
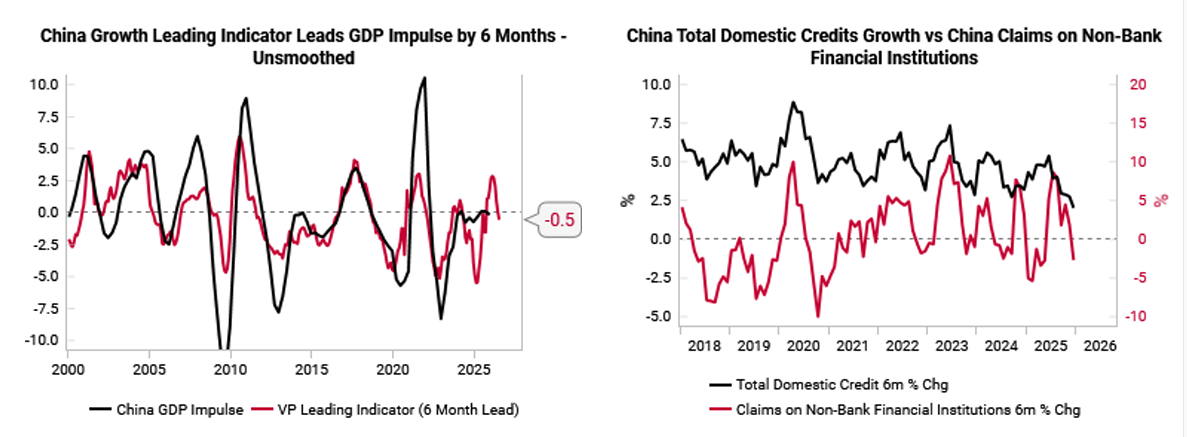
- China: Growth and liquidity have worsened, even as the structural weakness in the housing and consumer sectors persist.
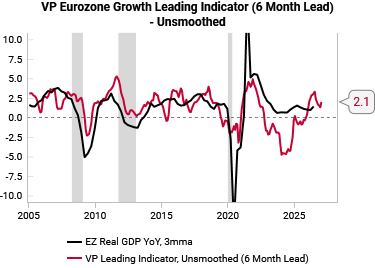
- Eurozone: Growth leading indicators are recovering, but structural headwinds suggest the balance of risks for EUR is still to the downside.
***
US
- Growth: Leading indicators remain steady
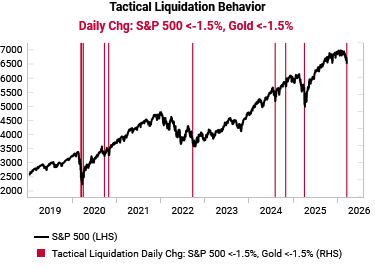
- Consumer: Consumption resilient in aggregate, credit stress bubbling up outside banks
- Labor: Base case remains jobless growth
- Inflation: Set to stay above target, but disinflationary impulses are building
China
- Growth: Leading indicator turns down, liquidity deteriorates
- RMB: Struggling to get excited about RMB strength
Eurozone
- Growth: Too late to embrace optimism, too early to feel structural headwinds
- EUR: Balance of risks for EUR still to the downside
***
Other Insights
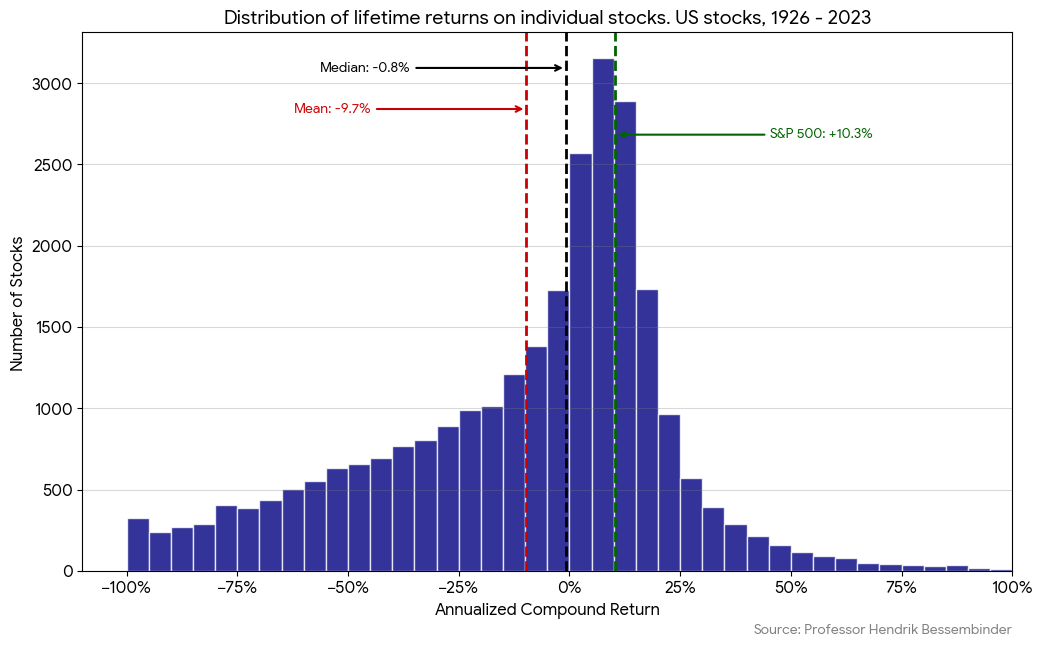
Practical insights on allocation, diversification, and risk tolerance—combining behavioral, liquidity, and structural perspectives.
Contact Us
Stay Connected
Our research is built for investors who need timely, repeatable insights.