

Hiking into weaker growth - G3 Leading Indicator Watch (Oct 6)
Central banks are hiking into weakening growth. The inflation impulse is already negative.
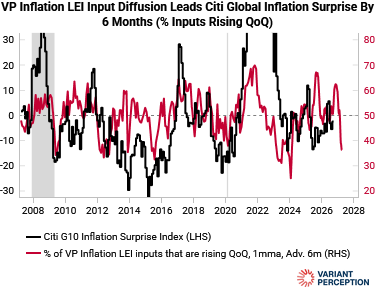
Our Inflation input diffusion is very weak. Outside energy, the trend is disinflation.

US Growth: Steady outlook. Fed hike signals transition to late-cycle environment
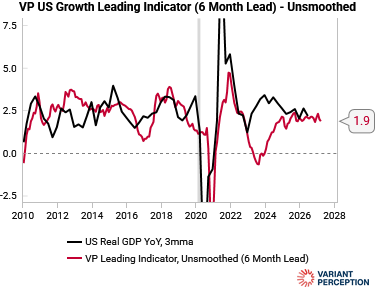
US growth leading indicator is still trending sideways at just under 2% annualised.That is well below GDPNow.

US Inflation breadth is surprisingly muted, while Iran and El Niño remain tail risks.
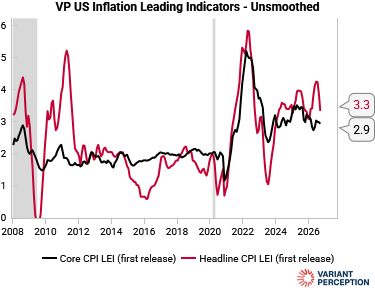
US Inflation leading indicators are still rolling over.
China Growth LEI weakens further on domestic demand drag, getting closer to policy pivot.
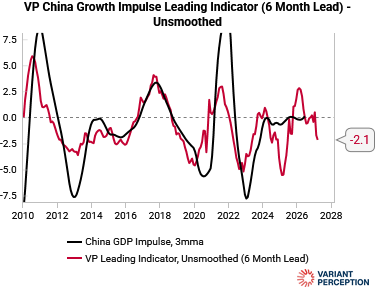
China growth impulse leading indicator has fallen four months straight.Weighing on it, is weak domestic demand.
Slowing Eurozone growth outlook, lagged effect of previous yield rises feeding through
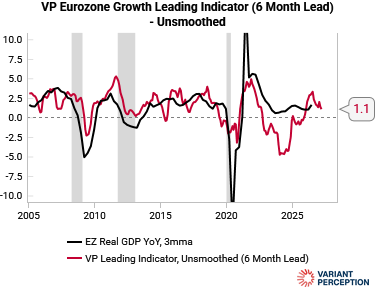
Our Eurozone growth leading indicator has continued to roll over, now falling to 1.1% annualized.
Visit Our Asset Allocation Dashboard
A summary of our investment ideas/portfolio positioning by time horizon.
[PREVIEW]
US Equities - Cyclical (6-12m)
- Our Macro Risk Indicator remains in “risk-on” territory, with growth, policy and liquidity overcoming an inflation component that has now turned "risk-off".
- US nominal growth is in line with IG yields. Watch for IG yields to rise above projected nominal growth as a warning sign.
- Within sectors, our fair value models see the most upside in semiconductors, energy, financials and communication services (Asset Allocation Engine).
- We continue to underweight the consumer sectors, where real-income headwinds should keep pressuring margins. Software continues to have the lowest capital cycle score among major sectors, while only offering mediocre value.
Other Insights
Practical insights on allocation, diversification, and risk tolerance—combining behavioral, liquidity, and structural perspectives.


Stay Connected
Our research is built for investors who need timely, repeatable insights.