Growth softer, tails wider - Sep. G3 Leading Indicator Watch
(Sep 10)
- Steady US growth outlook with balanced risks. Renewed services PMI strength is the upside surprise to watch. Consumer still weak as real incomes flatten and the savings rate turns up.
- US Core inflation trends remain muted, but Iran and El Niño keep the energy and food tails outside policymakers' control.
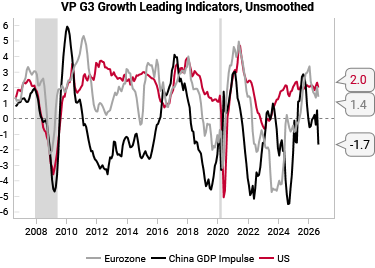
- In a reversal of last month's improvement, China growth LEI fell. Domestic demand are weak, but not yet near conditions before Oct 2024 policy pivot. We stay long EURCNH.
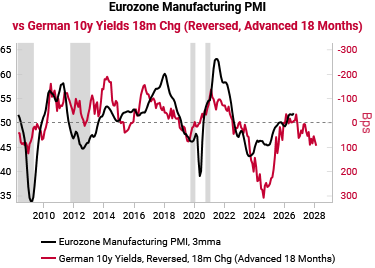
- Our Eurozone growth LEI gave back last month's improvement. Energy costs and lagged yield rises bite. Sticky services inflation and abnormally low gas storage keep stagflationary tail risks alive into winter.
US
- Growth: Steady with balanced risks, but renewed services strength a surprise to watch
- Consumer: Real income headwinds persist, savings rate starting to rise
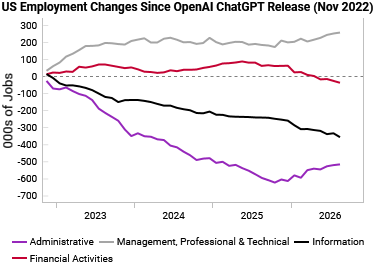
- Labor: Broadly in balance, not inflationary, AI job impact visible in exposed sectors
- Inflation: Trimmed mean PCE still falling, but Iran and El Niño beyond policymaker control
China
- Economy: Growth LEI drops as weak domestic economy persists
- FX: Stay long EURCNH as the path of least political resistance
Eurozone
- Growth: Growth LEI reverses improvement, as headwinds build from energy and yields
- Inflation: Sticky services inflation, low nat gas inventories remain tail risk into winter
Other Insights
Practical insights on allocation, diversification, and risk tolerance—combining behavioral, liquidity, and structural perspectives.

Contact Us
Stay Connected
Our research is built for investors who need timely, repeatable insights.