Politics Trumps Economics - Macro Snapshot
(Sep 2)
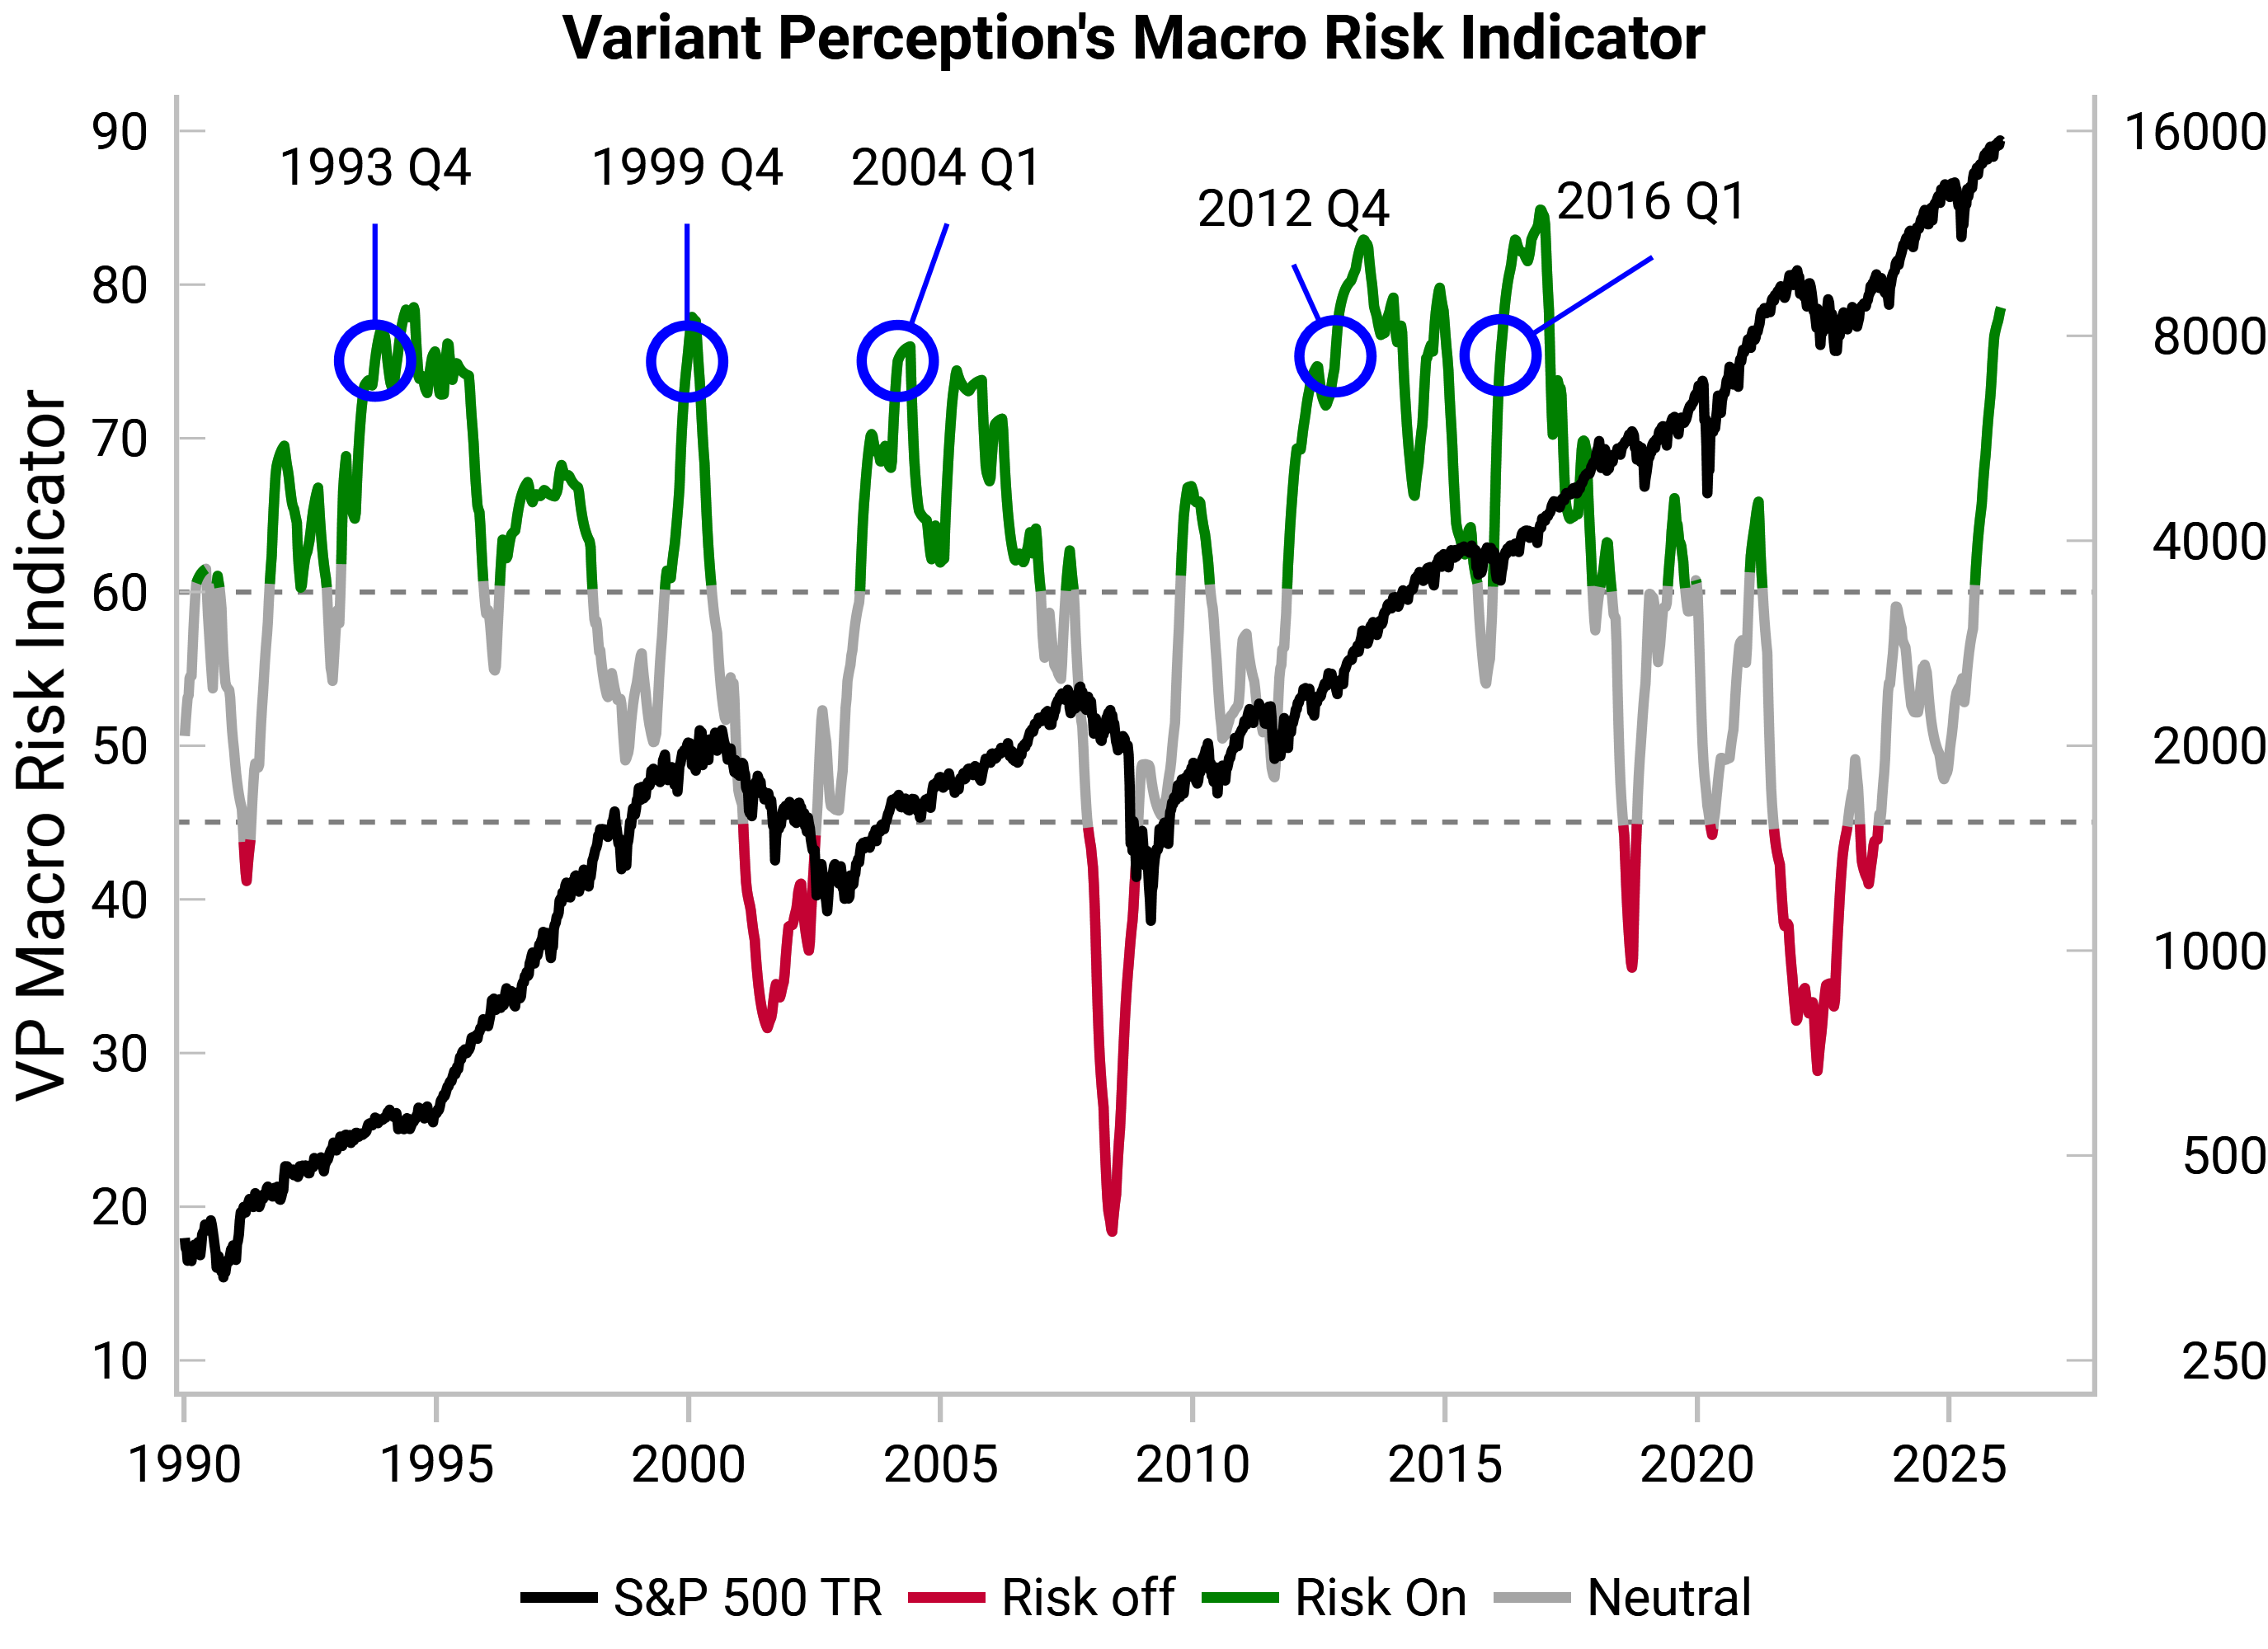
- Our Macro Risk Indicator remains "risk-on". Growth, policy and liquidity overcome an inflation component that has now turned "risk-off".
- US nominal growth is in line with IG yields. Watch for IG yields above projected nominal growth as a warning sign.
- The inflation scare is driven by energy and food, not underlying core trends. The Dallas Fed trimmed mean PCE is still trending down. Watch for 2s5s10s to turn positive as a warning sign that equities are vulnerable to a drawdown.
- Politics remains the dominant variable in fixed income and FX. Fed-Treasury coordination is capping the long end. USD weaponization fuels the bid for gold.
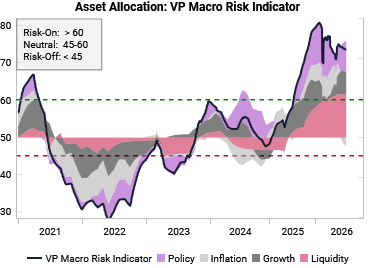
Cyclical Asset Allocation: Macro Risk Indicator remains "risk-on", overcoming inflation headwinds
Inflation (1): Core inflation trends remain moderate, trimmed mean PCE still falling…
Inflation (2): …but Iran conflict + El Niño tail risks keep markets on edge
Fed-Treasury Coordination: Politics caps the long end, but stock-bond correlations to remain positive
AI Bubble Watch: Equity breadth still good, watching Cisco/Sycamore/Juniper analogs
-
Equity: Earnings momentum persists, expectations remain very optimistic
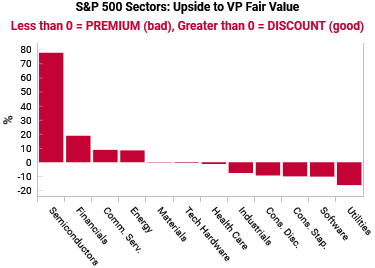
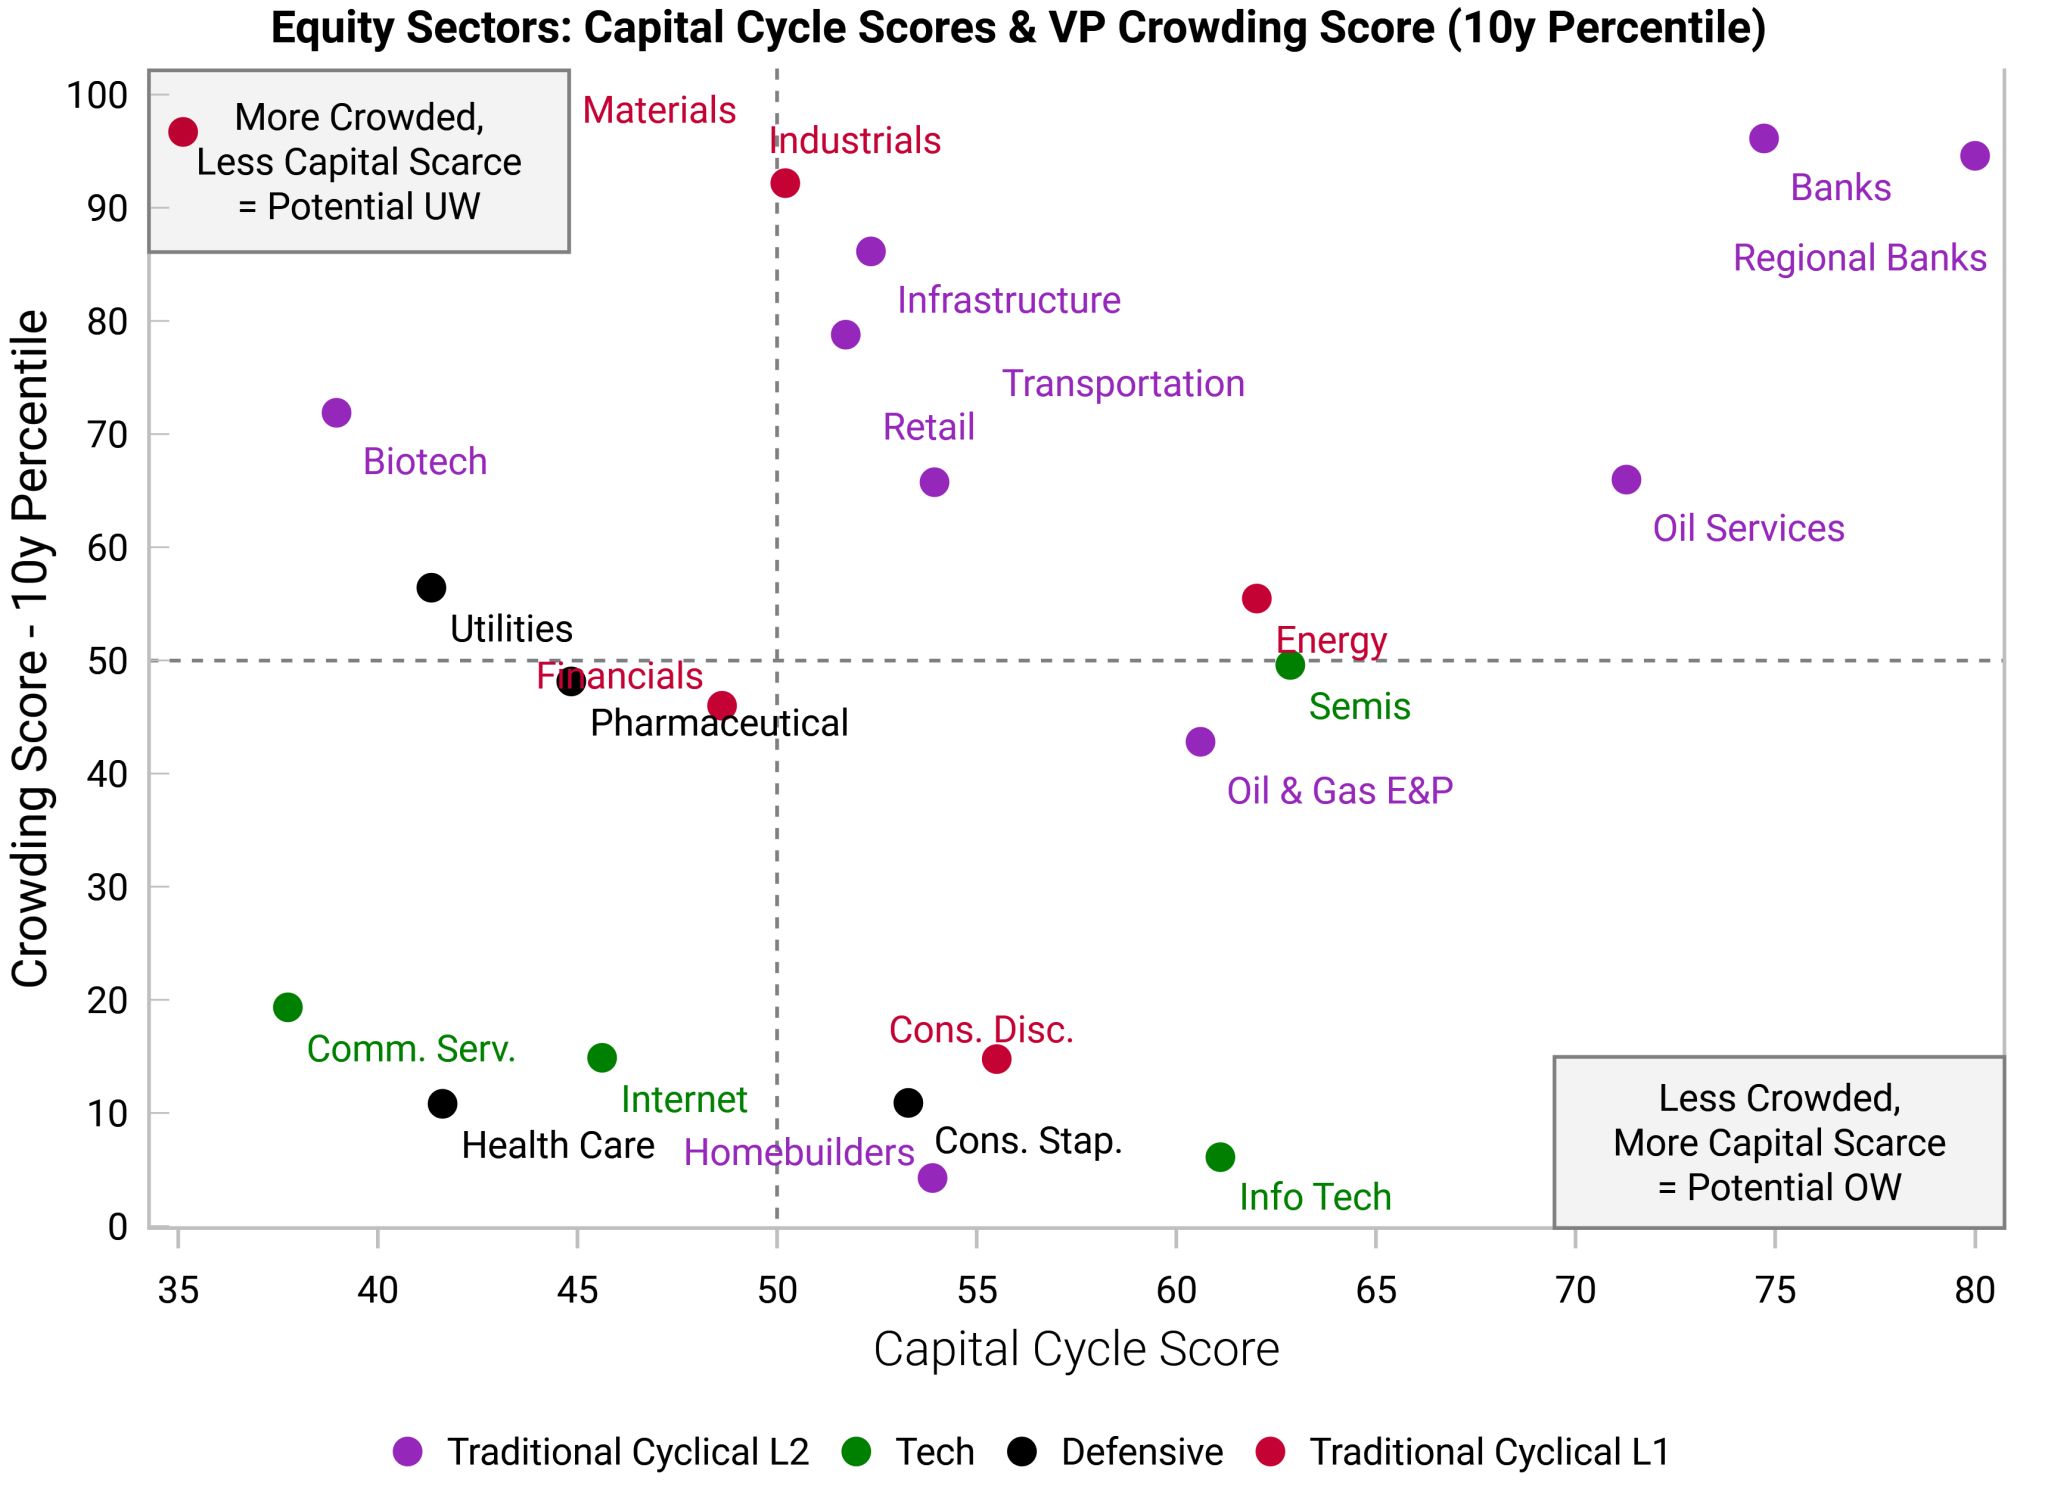
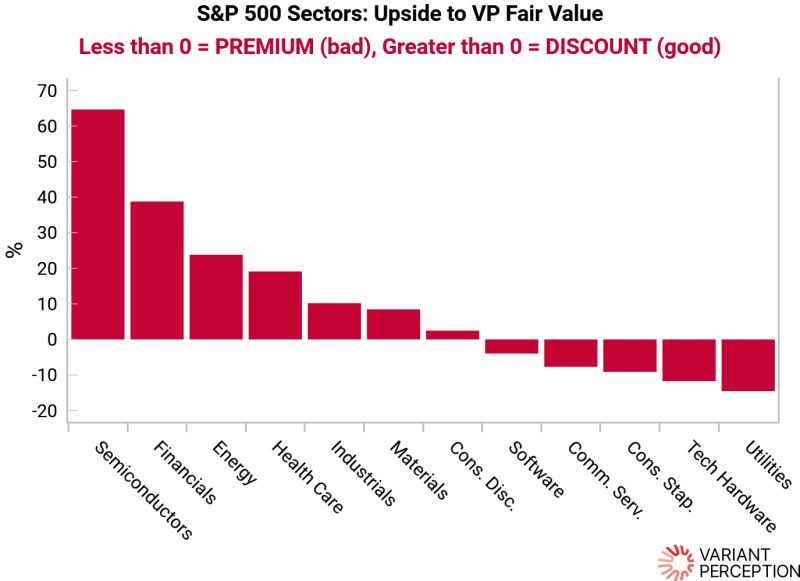
Sector Allocation: OW: Semis, Energy, Financials, Comm. Serv. UW: Consumer, Software
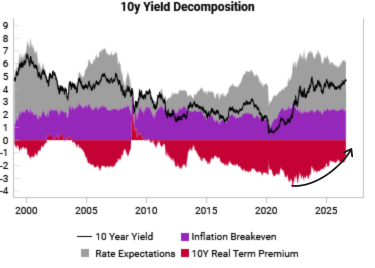
Fixed Income: Watch 2s5s10s for signs the Fed is offside, real term premium rise is normalization
FX: Politics trumps economics as the trend towards USD weaponization continues
Commodities: Cyclical macro regime moderately weaker, but structural gold bid is unchanged
Other Insights
Practical insights on allocation, diversification, and risk tolerance—combining behavioral, liquidity, and structural perspectives.
Stay Connected
Our research is built for investors who need timely, repeatable insights.